2026 Top Paper Board Paper Manufacturers Worldwide
The 2026 global paper market is becoming more specialized, competitive, and closely measured. This guide examines leading Paper Board Paper manufacturers across major producing regions, including Europe, Asia, North America, and Latin America. It focuses on measurable performance rather than reputation alone.
Manufacturers are assessed through production capacity, mill locations, product consistency, fiber sourcing, recycling systems, and delivery reliability. Technical factors also matter. Buyers may compare grammage, caliper, moisture levels, stiffness, edge crush strength, and printability. A carton that looks strong in a showroom may weaken after transport or humidity exposure. That detail deserves attention.
The guide also considers food-contact suitability, environmental certifications, energy use, and public sustainability reporting. These points can help packaging companies, distributors, and procurement teams make more informed decisions. However, rankings are not permanent. Capacity changes, acquisitions, energy prices, and regional logistics can quickly alter a manufacturer’s position. Public data is also inconsistent.
That is the difficult part.
Some companies publish detailed mill-level information, while others provide broad corporate figures. Therefore, this overview uses available evidence carefully and encourages readers to verify specifications directly with manufacturers. Samples, laboratory tests, audit records, and delivery trials remain valuable. A strong brochure is not proof of dependable supply.
The manufacturers featured here represent important industry capabilities, but no single company fits every application. Cost, performance, sustainability goals, and local service must be weighed together. This introduction is intended to provide a practical starting point for evaluating the world’s top Paper Board Paper producers in 2026.
Global Overview of the Paper Board Manufacturing Industry in 2026
In 2026, the paperboard industry is shaped by packaging demand, recycling targets, and regional manufacturing capacity. FAO statistics estimate global paper and paperboard production at more than 400 million tonnes annually. Packaging grades account for a major share of this volume. E-commerce still supports demand for corrugated board, while food packaging requires cleaner, stronger fiber materials.
Regional differences remain significant. Asia produces the largest share of global paperboard, supported by expanding consumer markets and converting capacity. Europe focuses more heavily on recycled fiber, energy efficiency, and formal circularity targets. North America continues investing in lightweight containerboard and automated plants. Smithers market analysis indicates continued growth in packaging papers through the decade, although forecasts vary by grade and region.
Manufacturers are facing tighter margins. Energy prices, recovered-paper quality, and water consumption affect operating costs directly. The Confederation of European Paper Industries reports that recycling remains central to the region’s fiber strategy, but collection systems do not perform equally everywhere. That gap matters.
Technical performance is also changing. Lightweight board must resist compression, moisture, and high-speed filling lines. Some mills are improving strength through fiber engineering rather than simply adding material. However, industry forecasts are not promises. Trade disruptions, weak construction activity, and uncertain consumer spending can quickly alter production plans. Public data also differs between agencies, so comparisons require careful definitions.
Leading Paper Board Manufacturers by Region and Production Capacity
2026 Top Paper Board Paper Manufacturers Worldwide
Leading paperboard manufacturers are best compared by regional capacity, operating output, and product mix. Asia remains the largest production center, supported by strong carton demand, expanding food delivery, and major recycled-fiber networks. FAO forestry statistics place global paper and paperboard production above 400 million tonnes annually. However, reported capacity differs between mills, especially when temporary closures or machine conversions occur.
Europe maintains a technically advanced base, with strong volumes in folding carton, corrugated case materials, and specialty board. CEPI industry statistics have placed European paper and board production near 80 million tonnes in recent reporting years. North America remains influential through large integrated mills and stable containerboard demand. Latin America benefits from renewable fiber resources, while the Middle East and Africa are developing smaller, import-sensitive production clusters. Capacity alone can mislead. A modern machine may produce more, but local fiber, energy, and logistics decide its real competitiveness.
Tips: Compare annual output with installed capacity. Check mill locations, recycled content, energy sources, and certification systems. Smithers market research also highlights packaging growth as a central demand driver through the decade. Buyers should request the latest mill data, not rely on old directories. That sounds obvious. It is often missed. Regional rankings also need caution because public figures may combine paper, board, and converted products. Some estimates remain incomplete.
2026 Top Paper Board Paper Manufacturers Worldwide - Leading Paper Board Manufacturers by Region and Production Capacity
Regional comparison of paperboard manufacturing capacity, estimated output, utilization, and principal product segments. Figures represent regional industry aggregates rather than individual companies or brands.
| Rank |
Region |
Estimated Annual Paperboard Capacity
(Million Metric Tonnes) |
Estimated 2025 Output
(Million Metric Tonnes) |
Average Capacity Utilization |
Key Paperboard Grades |
Primary End-Use Markets |
2026 Capacity Growth Outlook |
Recycled Fibre Share
(Estimated) |
| 1 |
Asia-Pacific |
145.0 |
128.2 |
88.4% |
Containerboard, folding boxboard, coated board, liquid packaging board |
E-commerce packaging, food and beverage, consumer goods, retail packaging |
4.5%–6.0% |
Approximately 63% |
| 2 |
Europe |
62.0 |
52.1 |
84.0% |
Recycled containerboard, cartonboard, solid board, specialty board |
Food packaging, pharmaceuticals, beverages, industrial packaging |
2.0%–3.5% |
Approximately 57% |
| 3 |
North America |
54.0 |
46.7 |
86.5% |
Containerboard, kraftliner, recycled linerboard, coated boxboard |
Transport packaging, foodservice, beverages, household products |
1.5%–2.5% |
Approximately 52% |
| 4 |
Latin America |
22.0 |
18.1 |
82.3% |
Kraftliner, containerboard, folding boxboard, liquid packaging board |
Food and beverage, agricultural products, personal care, exports |
3.0%–5.0% |
Approximately 39% |
| 5 |
Middle East |
7.0 |
5.3 |
75.7% |
Containerboard, corrugating medium, folding boxboard, solid board |
Food processing, logistics, retail, construction-related packaging |
4.0%–6.0% |
Approximately 34% |
| 6 |
Africa |
6.0 |
4.1 |
68.3% |
Recycled containerboard, cartonboard, corrugating medium |
Food and beverage, agriculture, household goods, local distribution |
5.0%–8.0% |
Approximately 31% |
| 7 |
Oceania |
3.0 |
2.4 |
80.0% |
Containerboard, recycled board, folding boxboard, specialty board |
Food exports, beverage packaging, agriculture, retail distribution |
0.5%–1.5% |
Approximately 46% |
| Total |
Worldwide |
299.0 |
256.9 |
85.9% weighted average |
Global paperboard capacity includes packaging board, containerboard, cartonboard, solid board, and selected specialty board grades. |
Methodology and scope: Capacity figures are regional industry estimates for installed and operational paperboard and packaging-board production lines. Output is estimated from reported regional production trends and utilization levels. The table excludes named manufacturers, brands, and individual mill-level figures. Percentages are rounded and may not total exactly because of regional estimation and rounding differences.
Reference basis: Compiled using publicly available information from FAO forestry and forest-products statistics, CEPI industry statistics, AF&PA statistical releases, regional packaging associations, recycling reports, and published 2024–2025 industry capacity announcements. Data availability varies by region; figures should be used for market comparison rather than audited financial reporting.
Major Paper Board Grades, Products, and Manufacturing Technologies
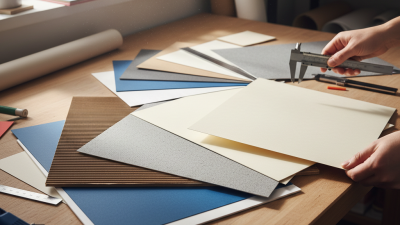
Worldwide paper board manufacturing covers several grades, each designed for a specific conversion need. Folding boxboard offers a smooth surface for retail printing and light packaging. White-lined chipboard often combines a bright top layer with recycled inner fibers. Corrugated medium provides fluting strength, while kraft board supports heavier loads. Coated grades improve color reproduction, but uncoated surfaces can feel more natural.
Modern mills use recycled fiber cleaning, chemical pulping, refining, and controlled sheet forming. Advanced presses monitor moisture, basis weight, thickness, and formation continuously. Calendering creates a more even surface. Barrier coatings can improve resistance to grease, water, or vapor. Still, no technology solves every problem. Higher coating levels may reduce recyclability or increase drying energy. Mill data also needs independent testing.
Tips: Match board grade with product weight, folding design, humidity, and printing method. Check Cobb water absorption, edge crush strength, bending stiffness, and surface roughness. Request samples from the actual production line, not only laboratory sheets. A short trial can reveal cracking at fold lines, weak glue bonding, or ink set-off. These details often matter more than a impressive specification sheet. Procurement teams should also review fiber origin, recycled content, wastewater controls, and quality consistency across batches. Temperature and storage conditions can quietly change board performance.
Key Factors for Evaluating Paper Board Manufacturers Worldwide
2026 Top Paper Board Paper Manufacturers Worldwide
Choosing among the 2026 top paper board manufacturers worldwide requires more than comparing price lists. Buyers should examine board caliper, basis weight, stiffness, moisture resistance, and surface smoothness. These details affect folding accuracy, print quality, stacking strength, and waste rates. A reliable manufacturer provides current laboratory data, clear tolerances, and samples from ordinary production, not only premium batches. Mill experience matters. So does consistency.
Tips: Request a trial order and inspect sheets after transport. Measure thickness at several points, test compression, and review fiber sources. Ask how recycled content is verified and whether forestry claims are independently audited. Check production capacity, backup equipment, export packaging, and realistic lead times. One overlooked detail is communication during quality disputes. Fast, documented answers often reveal stronger systems than impressive sales language.
Authority should be supported by evidence: recognized quality systems, traceability records, safety documentation, and independent test reports. Visit a mill when possible, or arrange a live remote audit. Compare results across seasons, because humidity can change board performance. I have found that the cheapest quotation may hide higher converting losses and delayed deliveries. Still, no checklist is perfect. A supplier may pass every test and miss a practical packing requirement. Recheck assumptions with operators, printers, and logistics teams before making a long-term decision.
2026 Top Paperboard Manufacturers Worldwide: Global Production Capacity
Regional paper and paperboard production provides a neutral benchmark for evaluating supplier scale, capacity availability, logistics coverage, and supply-chain resilience.
Asia represents the largest production base, followed by Europe and North America. When assessing paperboard manufacturers, buyers should compare production scale together with product quality consistency, recycled-fiber capability, energy efficiency, certification coverage, delivery reliability, and geographic proximity. Regional figures are rounded estimates for 2022 based on the FAO Forestry Production and Trade database.